
Tonight's highlights: U.S. Equity Futures Advance Across the Board; Nvidia Slumps 6% Premarket Against the Tape
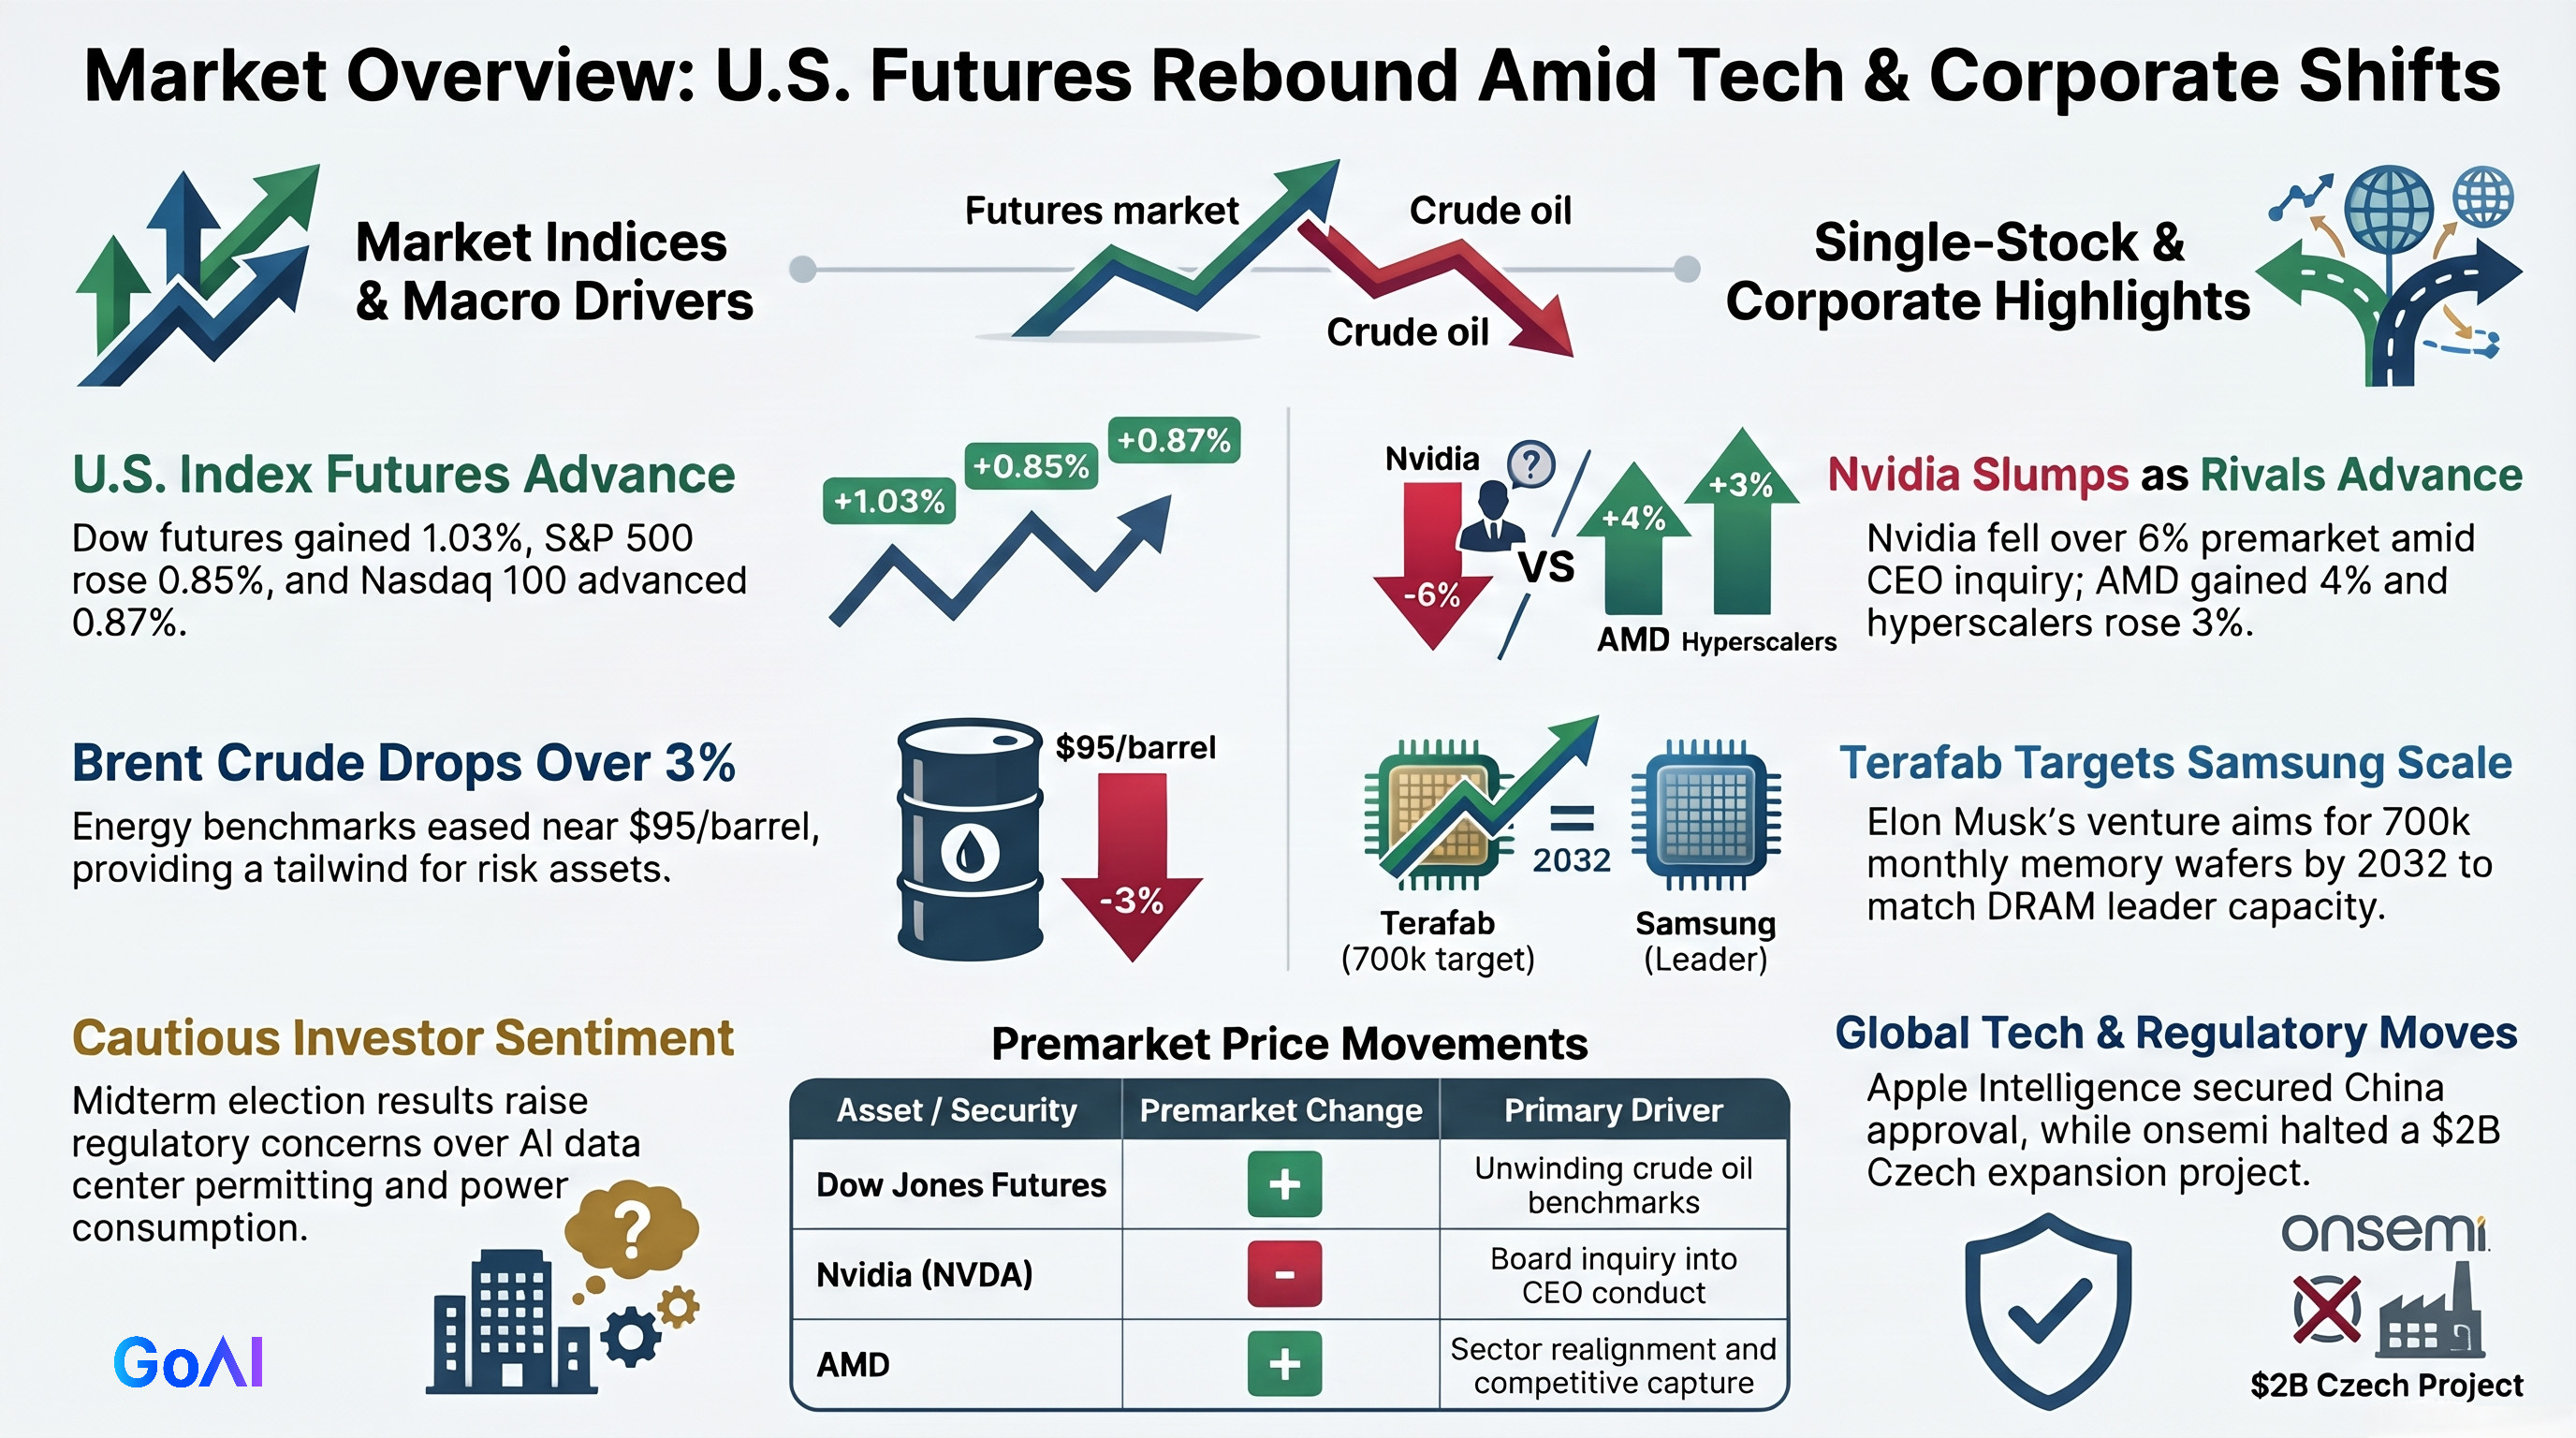
U.S. equity index futures pointed to a higher open on Monday, Nov. 9, with Dow futures gaining over 1% as crude benchmarks continued to unwind.
As of press time, Dow Jones Industrial Average futures gained 1.03%, S&P 500 futures advanced 0.85%, and Nasdaq 100 futures rose 0.87%.
The early bounce follows a bruising week for tech equities that saw all three major benchmarks log weekly declines, though the Nasdaq Composite and S&P 500 recouped a portion of their losses on Friday.
Easing energy benchmarks provided an underlying tailwind to risk assets. Front-month Brent crude fell more than 3% intraday to hover near $95 per barrel, extending its steepest weekly retreat since April 2020.
Despite the premarket bid, institutional sentiment remains cautious.
The Democratic sweep in last week's midterm elections has heightened concerns over regulatory pushback on hyperscale data-center permitting and power consumption, which could bottleneck the trajectory of AI infrastructure buildouts.
Liz Ann Sonders, chief investment strategist at Charles Schwab, noted that while both the Nasdaq Composite and Nasdaq 100 trade in technically oversold territory, retail investors are not aggressively buying the dip as they did in past cycles.
"We have seen significant net liquidation... the question is whether retail dip-buyers re-emerge at some point," Sonders remarked, advising market participants to focus near term on corporate capex adjustments and forward margin guidance.
Looking to the week ahead, investors are closely watching earnings reports from AI bellwethers CoreWeave, Cisco Systems, and Applied Materials to evaluate secular tech demand and determine whether the recent liquidation has fully run its course.
In single-stock action, Nvidia shares tumbled more than 6% premarket amid reports that an alleged extramarital affair involving Chief Executive Jensen Huang has prompted a board of directors inquiry. Conversely, chief rival AMD gained over 4%, while mega-cap hyperscalers Alphabet, Microsoft, and Amazon advanced roughly 3% each.
Across the Atlantic, European bourses pushed higher. Germany’s DAX gained 1.07%, the U.K.’s FTSE 100 rose 0.62%, and France’s CAC 40 climbed 0.73%.
Corporate & Sector Developments
Apple Intelligence Secures Regulatory Clearance in China for iPad and Mac: "Apple Intelligence" has completed the required regulatory filing under China’s Interim Measures for the Management of Generative AI Services, expanding formal approval to include Apple tablets and laptops, according to an announcement published by the Cyberspace Administration of Shanghai.
Musk’s Terafab Targets 700K Monthly Memory Wafers to Rival Samsung DRAM Scale: Elon Musk’s semiconductor venture, Terafab, is setting its sights on the core of global memory output. Terafab has reportedly outlined a target to equipment suppliers to reach 1 million wafer starts per month (WSPM) by 2032, comprising 700,000 memory wafers and 300,000 logic wafers.
A 700K memory run-rate would match the total global DRAM capacity of Samsung Electronics, which currently stands around 650,000 to 700,000 wafers per month, setting an ambitious hurdle for the startup to replicate industry-leading capacity within a six-year window.
Tesla Weighs Leasing Model for Optimus Humanoid Robots: Elon Musk stated that Tesla is likely to offer its Optimus humanoid robots under a lease arrangement rather than outright commercial sales. Tesla has initiated pilot production of Optimus at its Fremont factory, with customer deliveries targeted for late 2027.
GE Vernova Secures 16.5 MW German Wind Order: GE Vernova entered into an agreement with Stadtwerke Heidenheim AG to supply three 5.5 MW onshore wind turbines for the Schlotberg-Jüchsen wind park in Germany, representing 16.5 MW of total capacity alongside a 20-year full-service agreement.
The contract marks the sixth collaboration between the two firms, expanding Stadtwerke Heidenheim’s deployed GE Vernova fleet to 74 MW. Deliveries are scheduled to begin in August 2027 with commissioning by December 2027; the booking was finalized in Q4 2026.
House and Senate Democrats Prepare Congressional Inquiries into Musk and Miller: Democratic lawmakers confirmed Sunday that they intend to initiate formal congressional investigations into billionaire Elon Musk, White House Chief of Staff Stephen Miller, and selected corporate entities once Democrats take control of Congress in January.
The intent was outlined by Representative Robert Garcia and Senator Elizabeth Warren during televised appearances.
onsemi Halts $2 Billion Czech Silicon Carbide Expansion: onsemi and the Czech Ministry of Industry and Trade confirmed that they will not proceed with the previously announced multi-year expansion of up to $2 billion at the Rožnov pod Radhoštěm site.
Announced in June 2024, the project was intended to establish end-to-end silicon carbide (SiC) production. Existing silicon and SiC manufacturing operations at the Rožnov plant remain unaffected and will continue operating as part of onsemi’s global manufacturing footprint.
Sakana AI Targets Autumn 2027 IPO; Taps Goldman Sachs: Tokyo-based generative AI startup Sakana AI is preparing for an initial public offering, targeting a dual or sole listing in Japan or the United States as early as autumn 2027. The company has retained Goldman Sachs to steer the IPO process.