
Micron Delivers Blockbuster Earnings but Shares Stumble; Wall Street Stays Resolutely Bullish with Street-High Price Target of $1,625
Micron Technology Inc. beat Wall Street estimates across the board in its latest quarterly print, yet its shares saw a muted reaction in premarket trade following an extraordinary year-to-date run.
Despite the subdued price action, major investment banks remain overwhelmingly bullish on the memory maker’s multi-year earnings power in the AI era.
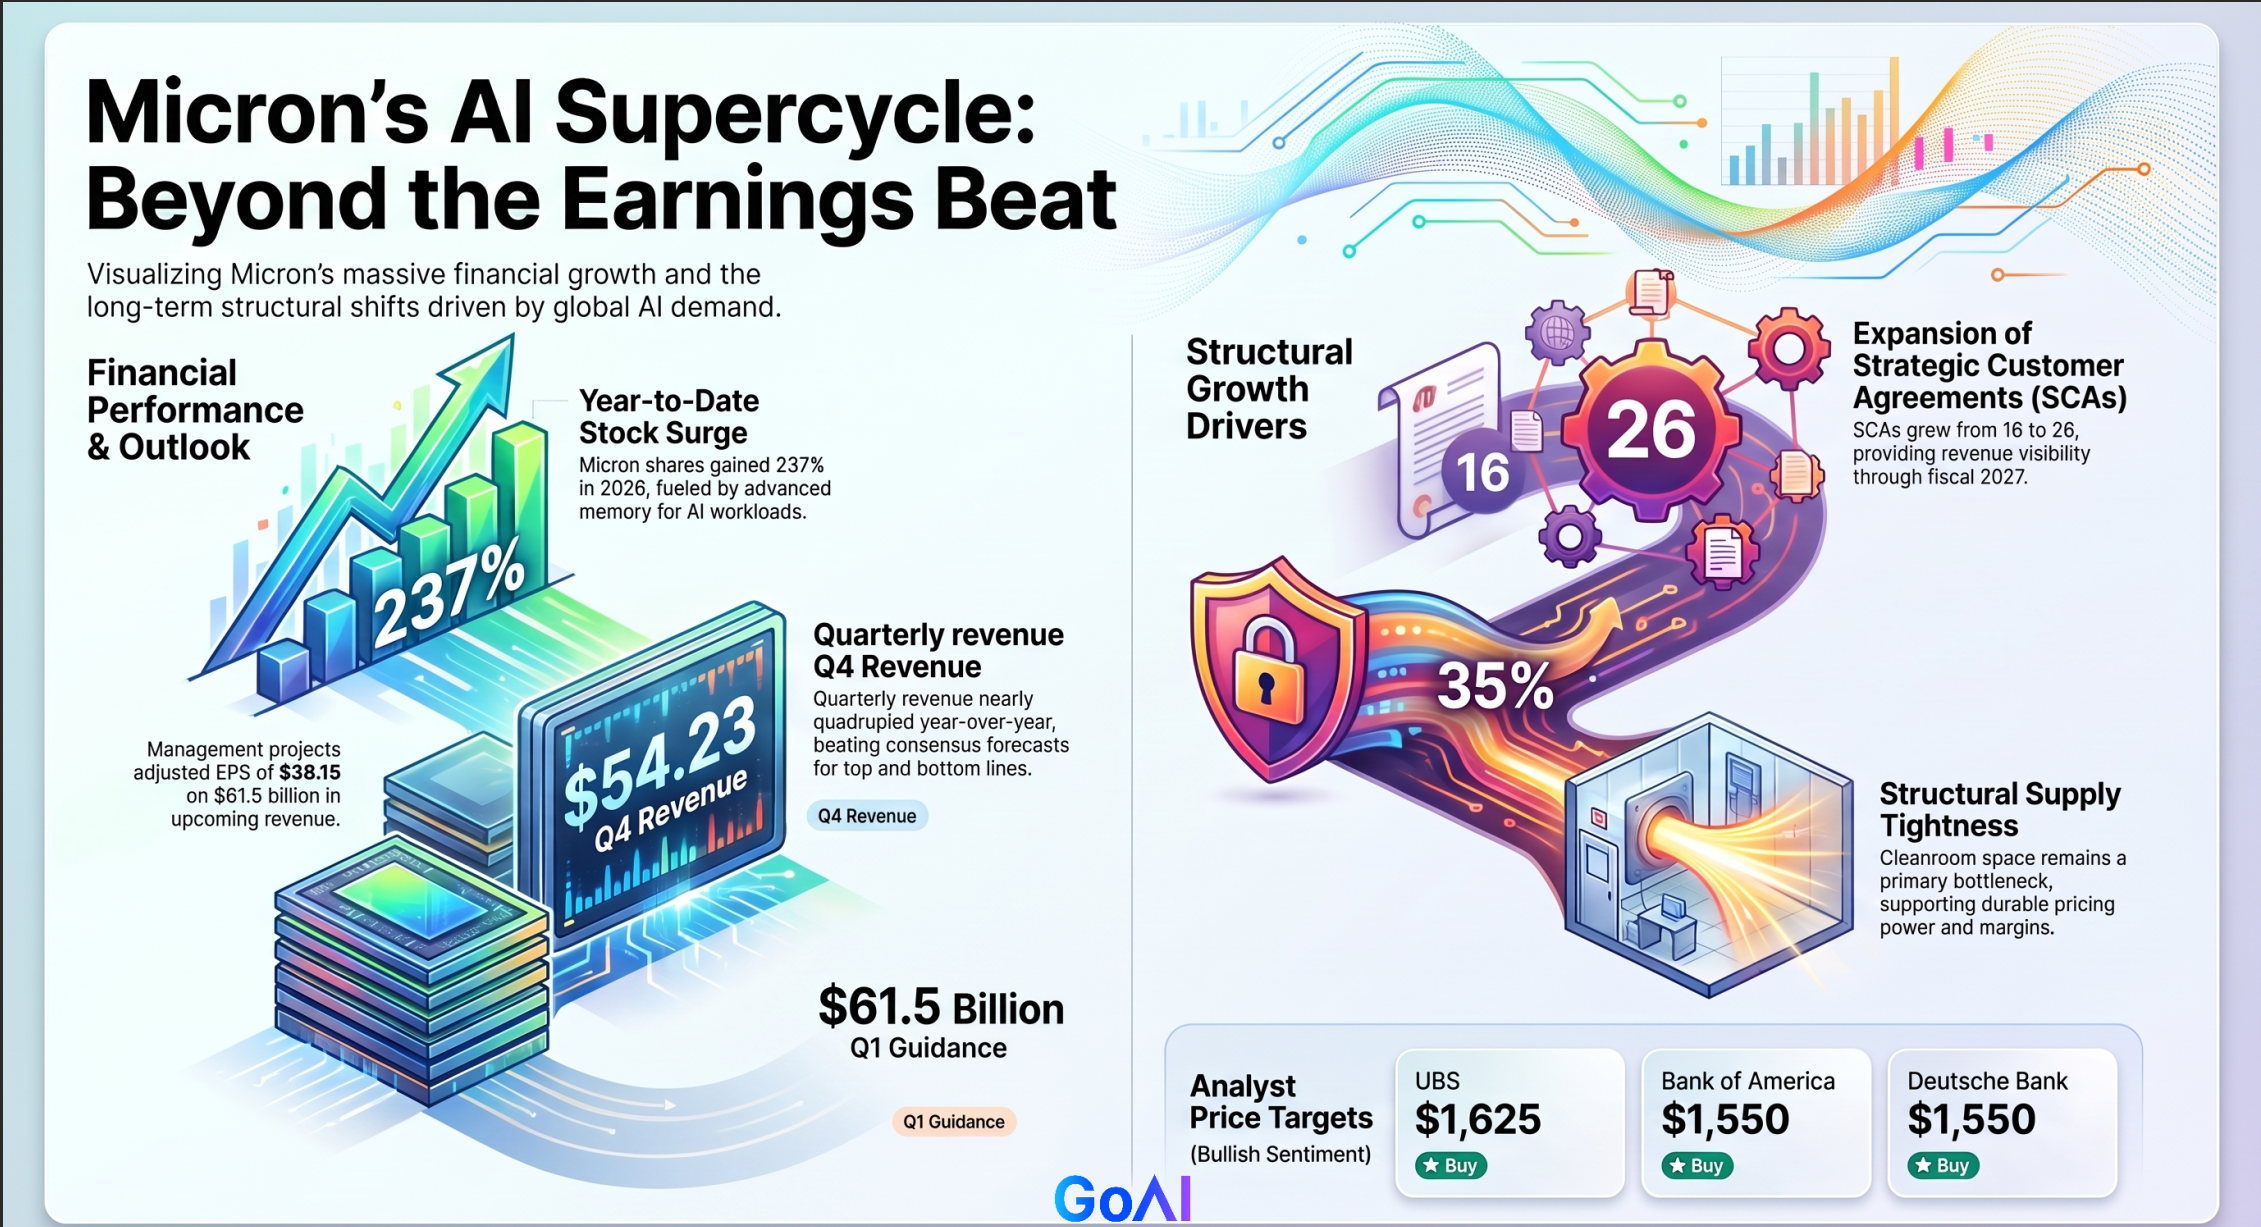
Fourth-quarter revenue surged to $54.23 billion—nearly quadrupling from a year ago—while adjusted earnings printed at $33.42 per share, with both top- and bottom-line metrics topping consensus forecasts.
Concurrently, management issued a robust first-quarter outlook, guiding revenue to approximately $61.5 billion and adjusted EPS to $38.15.
The stock was virtually unchanged in premarket trading following the report, a muted response that stands in sharp contrast to its blistering year-to-date performance.
Driven by an insatiable appetite for advanced memory chips across artificial intelligence workloads, Micron shares have gained 237% in 2026.
Wall Street was quick to look past the short-term pause, with several marquee brokerages reiterating their bullish ratings.
Analysts broadly argued that an expanding roster of multi-year strategic customer agreements, coupled with structural supply tightness across the memory complex, provides durable support for further upside.
AI Demand Secures Structural Fundamentals
Soaring AI adoption has catalyzed a historic re-rating in Micron shares this year, and Deutsche Bank expects that demand trajectory to strengthen further over the coming quarters, providing additional runway for the stock.
Deutsche Bank analyst Melissa Weathers told clients that the broader memory industry's fundamentals remain structurally sound for the foreseeable future.
She noted that while sentiment around the memory sector in an AI-driven cycle may remain volatile, Micron's idiosyncratic advantages and an exceptionally favorable supply-demand balance should support mid-cycle through-the-cycle earnings power well above historical trends.
Deutsche Bank reiterated its Buy rating on Micron alongside a $1,550 price target, implying roughly 46% upside from Wednesday's closing print.
Strategic Customer Agreements Boost Earnings Visibility
Sell-side desks converged around Micron's progress in securing long-term volume commitments and pricing power.
Bank of America observed that updated pricing frameworks for High-Bandwidth Memory (HBM), alongside the expansion of Strategic Customer Agreements (SCAs) from 16 to 26 over the quarter, give management unprecedented visibility into quarterly revenue and gross margin expansion through fiscal 2027.
Reaffirming its Buy rating and $1,550 price target, BofA projected that advanced memory will capture a larger share of the AI hardware profit pool in 2027 and beyond.
Goldman Sachs noted that the 10 newly signed long-term agreements account for roughly 35% of projected fiscal 2030 revenue, with approximately 75% of those volumes governed by structured pricing frameworks.
The bank views these pacts as a meaningful positive catalyst that should help expand the multiple investors are willing to pay on mid-cycle earnings.
JPMorgan likewise underscored that broader SCA coverage, tighter supply-demand projections, and a transparent capital return framework reinforce a durable multi-year earnings thesis for Micron.
Street Remains Resolutely Bullish; Street-High Target Hits $1,625
While Goldman Sachs cautioned that elevated buy-side expectations and modest incremental gross margin headwinds could temper near-term momentum, major sell-side firms maintained overwhelmingly positive ratings.
UBS set a Street-high price target of $1,625, reiterating a Buy rating.
UBS argued that the market will eventually grant the stock a higher valuation multiple.
The bank modeled a structural gross margin floor of 65% to 70%, noting that the indispensable role of memory in the AI paradigm will sustain elevated return on equity across the cycle.
Citi established a $1,300 price target, pointing out that cleanroom space remains the industry's primary supply bottleneck.
Micron's fiscal 2027 capex program is predominantly directed toward constructing cleanrooms slated for commercial deployment in late 2028 and beyond—a tangible signal of management's confidence in secular demand.
Morgan Stanley reiterated an Overweight rating with a $1,200 price target, concluding that while quarter-over-quarter growth rates may naturally moderate, underlying momentum remains exceptionally strong, with the longevity of this upcycle still underappreciated by broader capital markets.