
TSMC Q3 2026 Earnings Preview: Key Themes to Watch
TSMC is set to report its Q3 2026 financial results this Thursday after the Taiwan market close, followed by an earnings conference call at 2:00 PM local time. With the stock recently touching fresh all-time highs, market expectations have escalated in tandem.
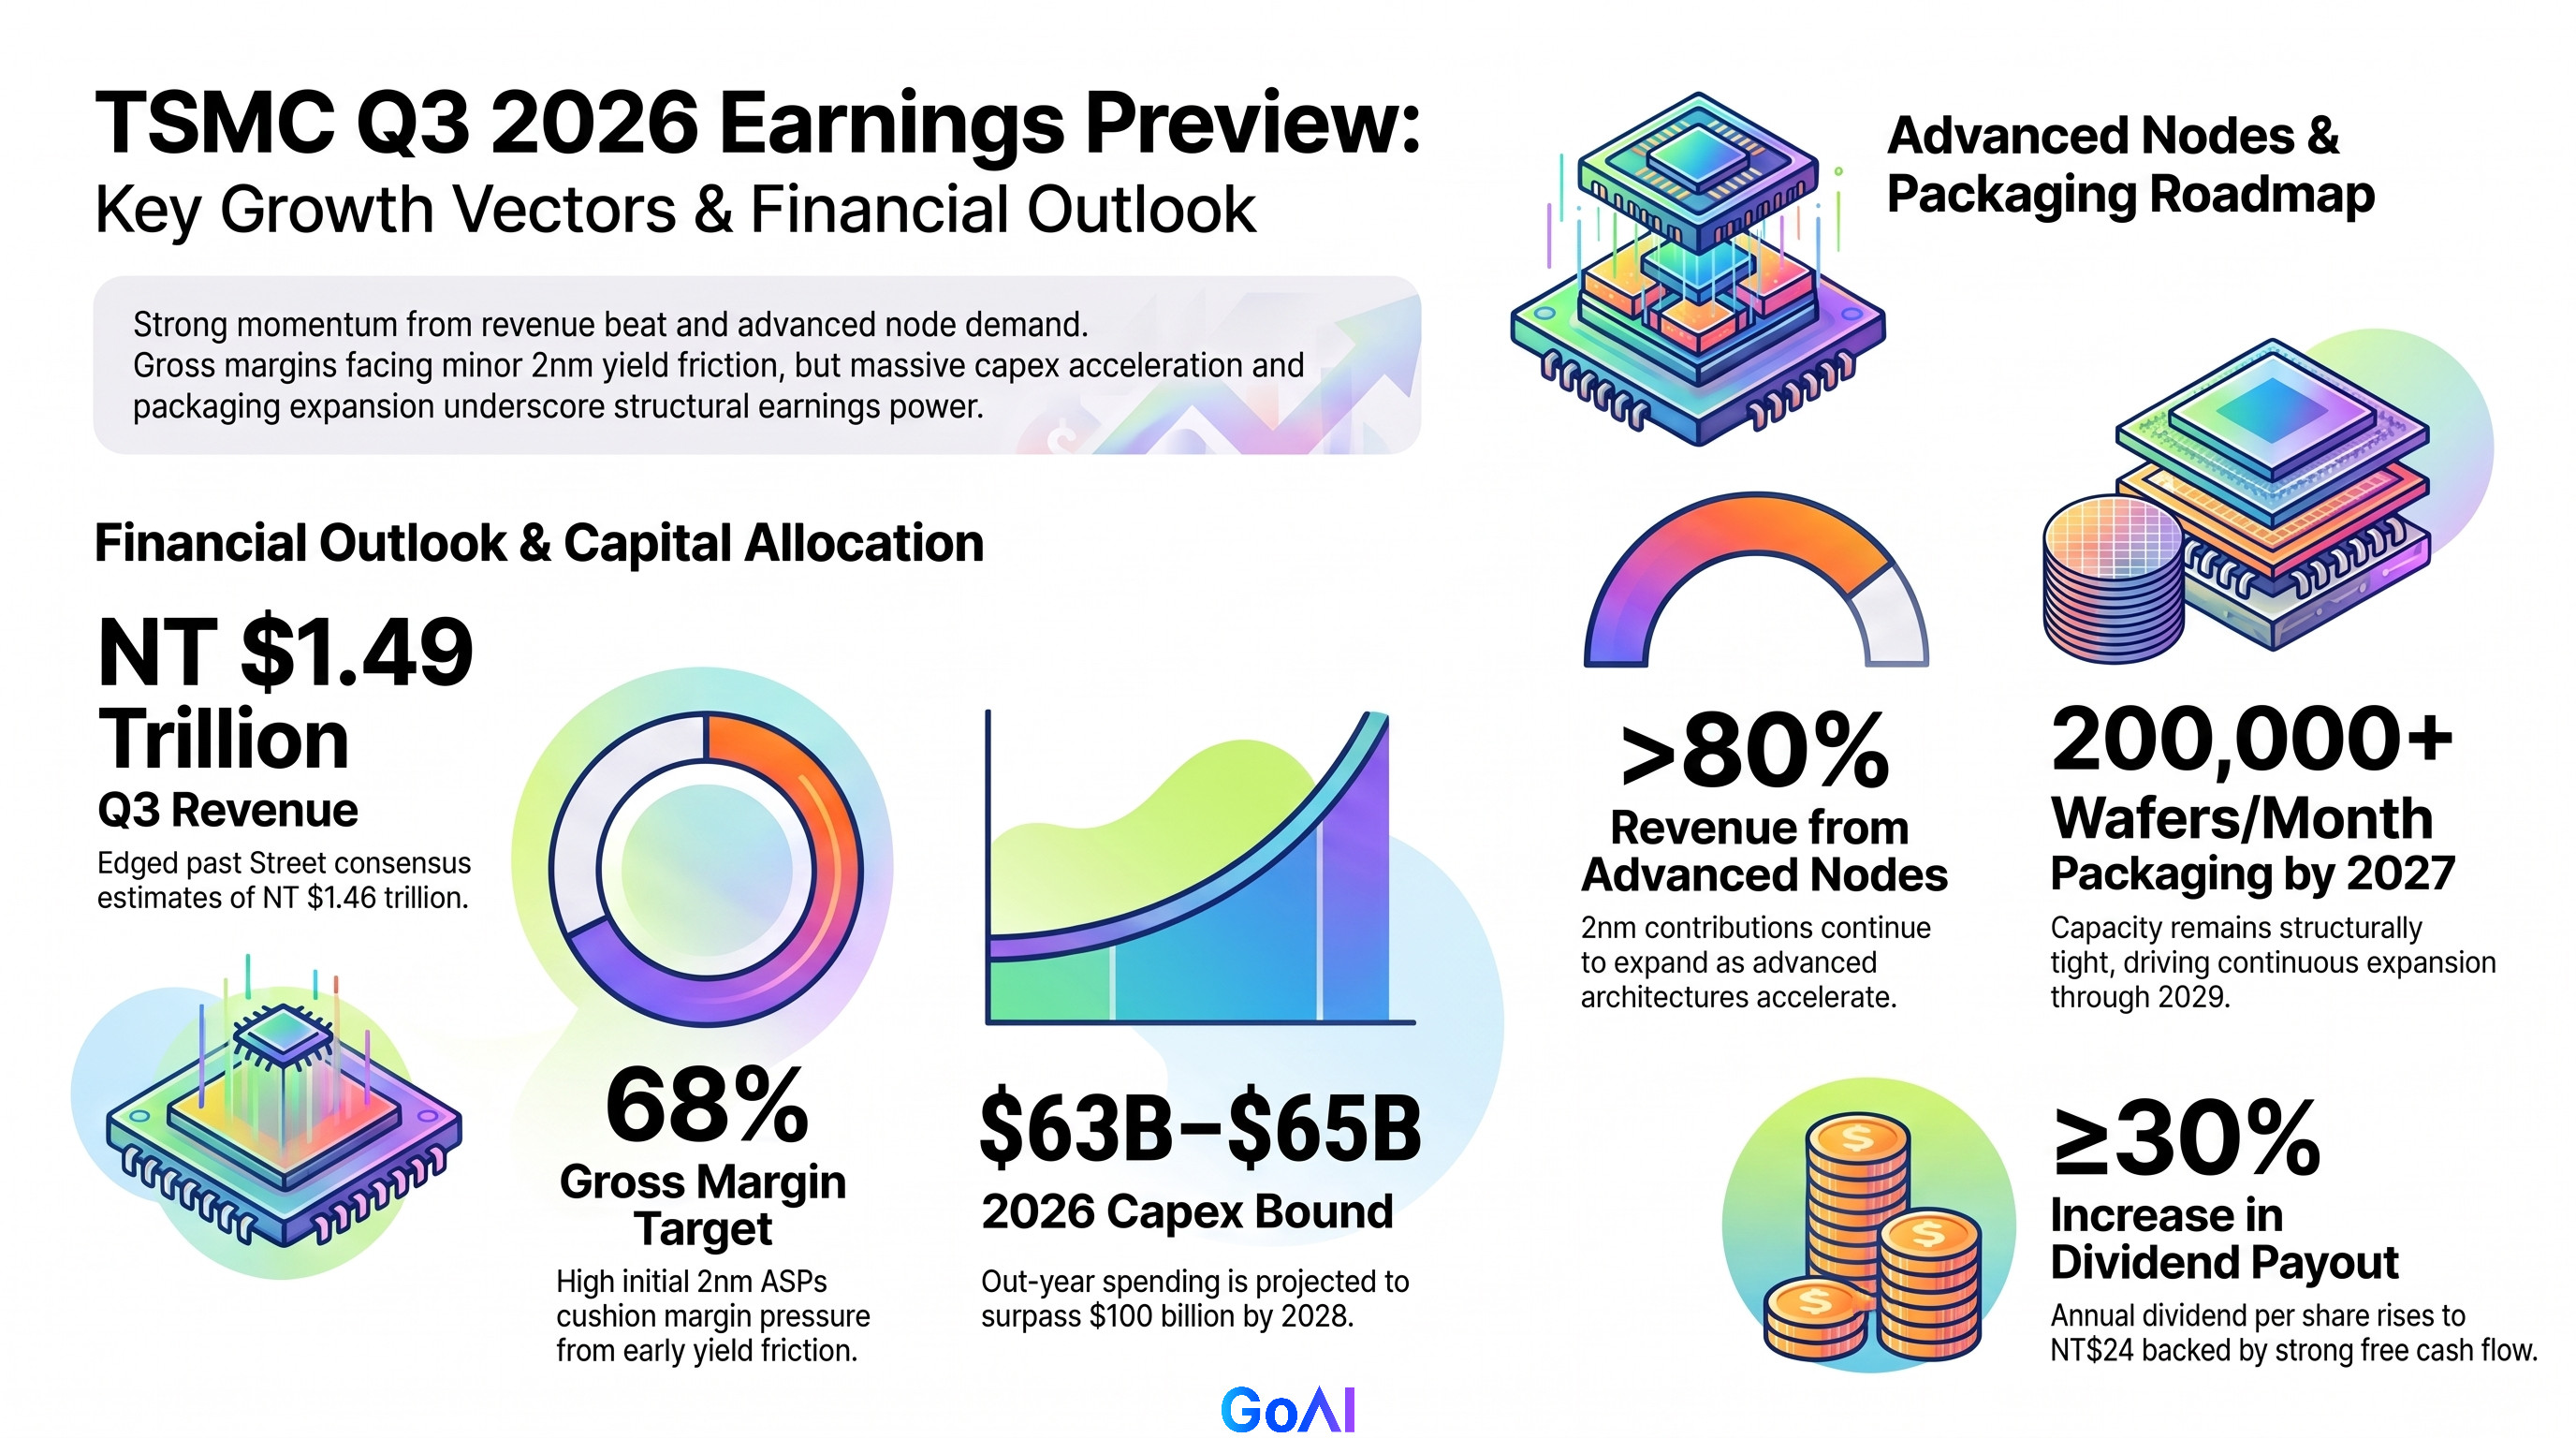
TSMC’s Q3 revenue printed at NT$1.49 trillion, edging past consensus estimates of NT$1.46 trillion in a result that largely matched elevated Street bogeys.
The Street models sequential top-line growth of 10% to 13% (in U.S. dollar terms) for the upcoming quarter and projects full-year expansion to hold above 30% next year.
Given the company's track record of topping guidance, market focus has pivoted primarily to gross margin sustainability, advanced nodes and packaging roadmaps, and forward capex projections.
On gross margins, TSMC previously guided toward 68%, while buyside bogeys sit closer to 69%.
Sell-side desks, however, caution that the 2nm ramp could dilute profitability toward the 67% mark, with lingering yield-learning friction and platform transitions potentially dragging margins to around 66% down the road.
That said, gross margins will likely meet guidance as premium average selling prices (ASPs) for initial 2nm allocations cushion the ramp-up curve.
On advanced nodes and packaging, the 2nm top-line contribution is poised to expand substantially, turning scrutiny toward whether other nodes are accelerating their transition to advanced architectures, as well as the cadence of foundry price hikes.
TSMC has signaled that pricing adjustments will remain measured, favoring gradual increases across the year to ensure customer absorption.
In advanced packaging, monthly capacity is projected at 140,000 wafers this year and over 200,000 in 2027, though supply remains structurally tight, necessitating further expansion through 2028–2029 to meet unconstrained demand.
Co-packaged optics (CoPoS) also represents a key roadmap vector slated for commercial debut in 2028. Overall, advanced nodes should eclipse 80% of total revenue, while packaging remains structurally overbooked.
On shareholder distributions, TSMC is widely expected to accelerate dividend payouts and share buybacks, echoing moves across memory peers. Management previously indicated that full-year DPS would rise by at least 30% to NT$24 per share.
Backed by abundant free cash flow, the company retains ample balance-sheet headroom to escalate distributions further.
On capex, full-year spending is poised to hit the upper bound of guidance at $63 billion to $65 billion, with potential for further upward revisions.
Out-year spending could swell to the $90 billion mark in 2027 before topping $100 billion by 2028. Naturally, an upward revision to capex could weigh on sentiment as an incremental drag on near-term cash flows, representing a key focal point for investors.
We maintain a $520 price target per ADR, which offers continued upside from Friday's close and implies an adjusted forward P/E of roughly 30x—still reasonable given TSMC's structural earnings power.
That said, investors should brace for tactical choppiness and headline volatility over the near term.