
Meta Q3 2026: Advertising Is Funding AI, and Muse May Be Opening the Next Door
In our view, the real takeaway from Meta's earnings was not that revenue beat expectations by a little over a billion dollars, nor that adjusted EPS looked far stronger once the legal charge was removed.
The more important point is that Meta is showing a rare combination: its legacy business is still generating powerful cash flows, its next business is beginning to take shape, and management is willing to redeploy the cash from the first into AI at extraordinary speed.
That is why the market's reaction is understandably mixed.
Bulls see an advertising business that has not slowed while the company spends aggressively on AI—and may in fact be getting stronger because of AI.
Skeptics see capital spending increasingly resembling that of a company building industrial-scale infrastructure, rather than the asset-light, free-cash-flow-rich internet platform Meta used to be. Both views have merit.
The real question is which one will prove more important over the next several years.
Advertising remains Meta's hardest-to-replicate advantage
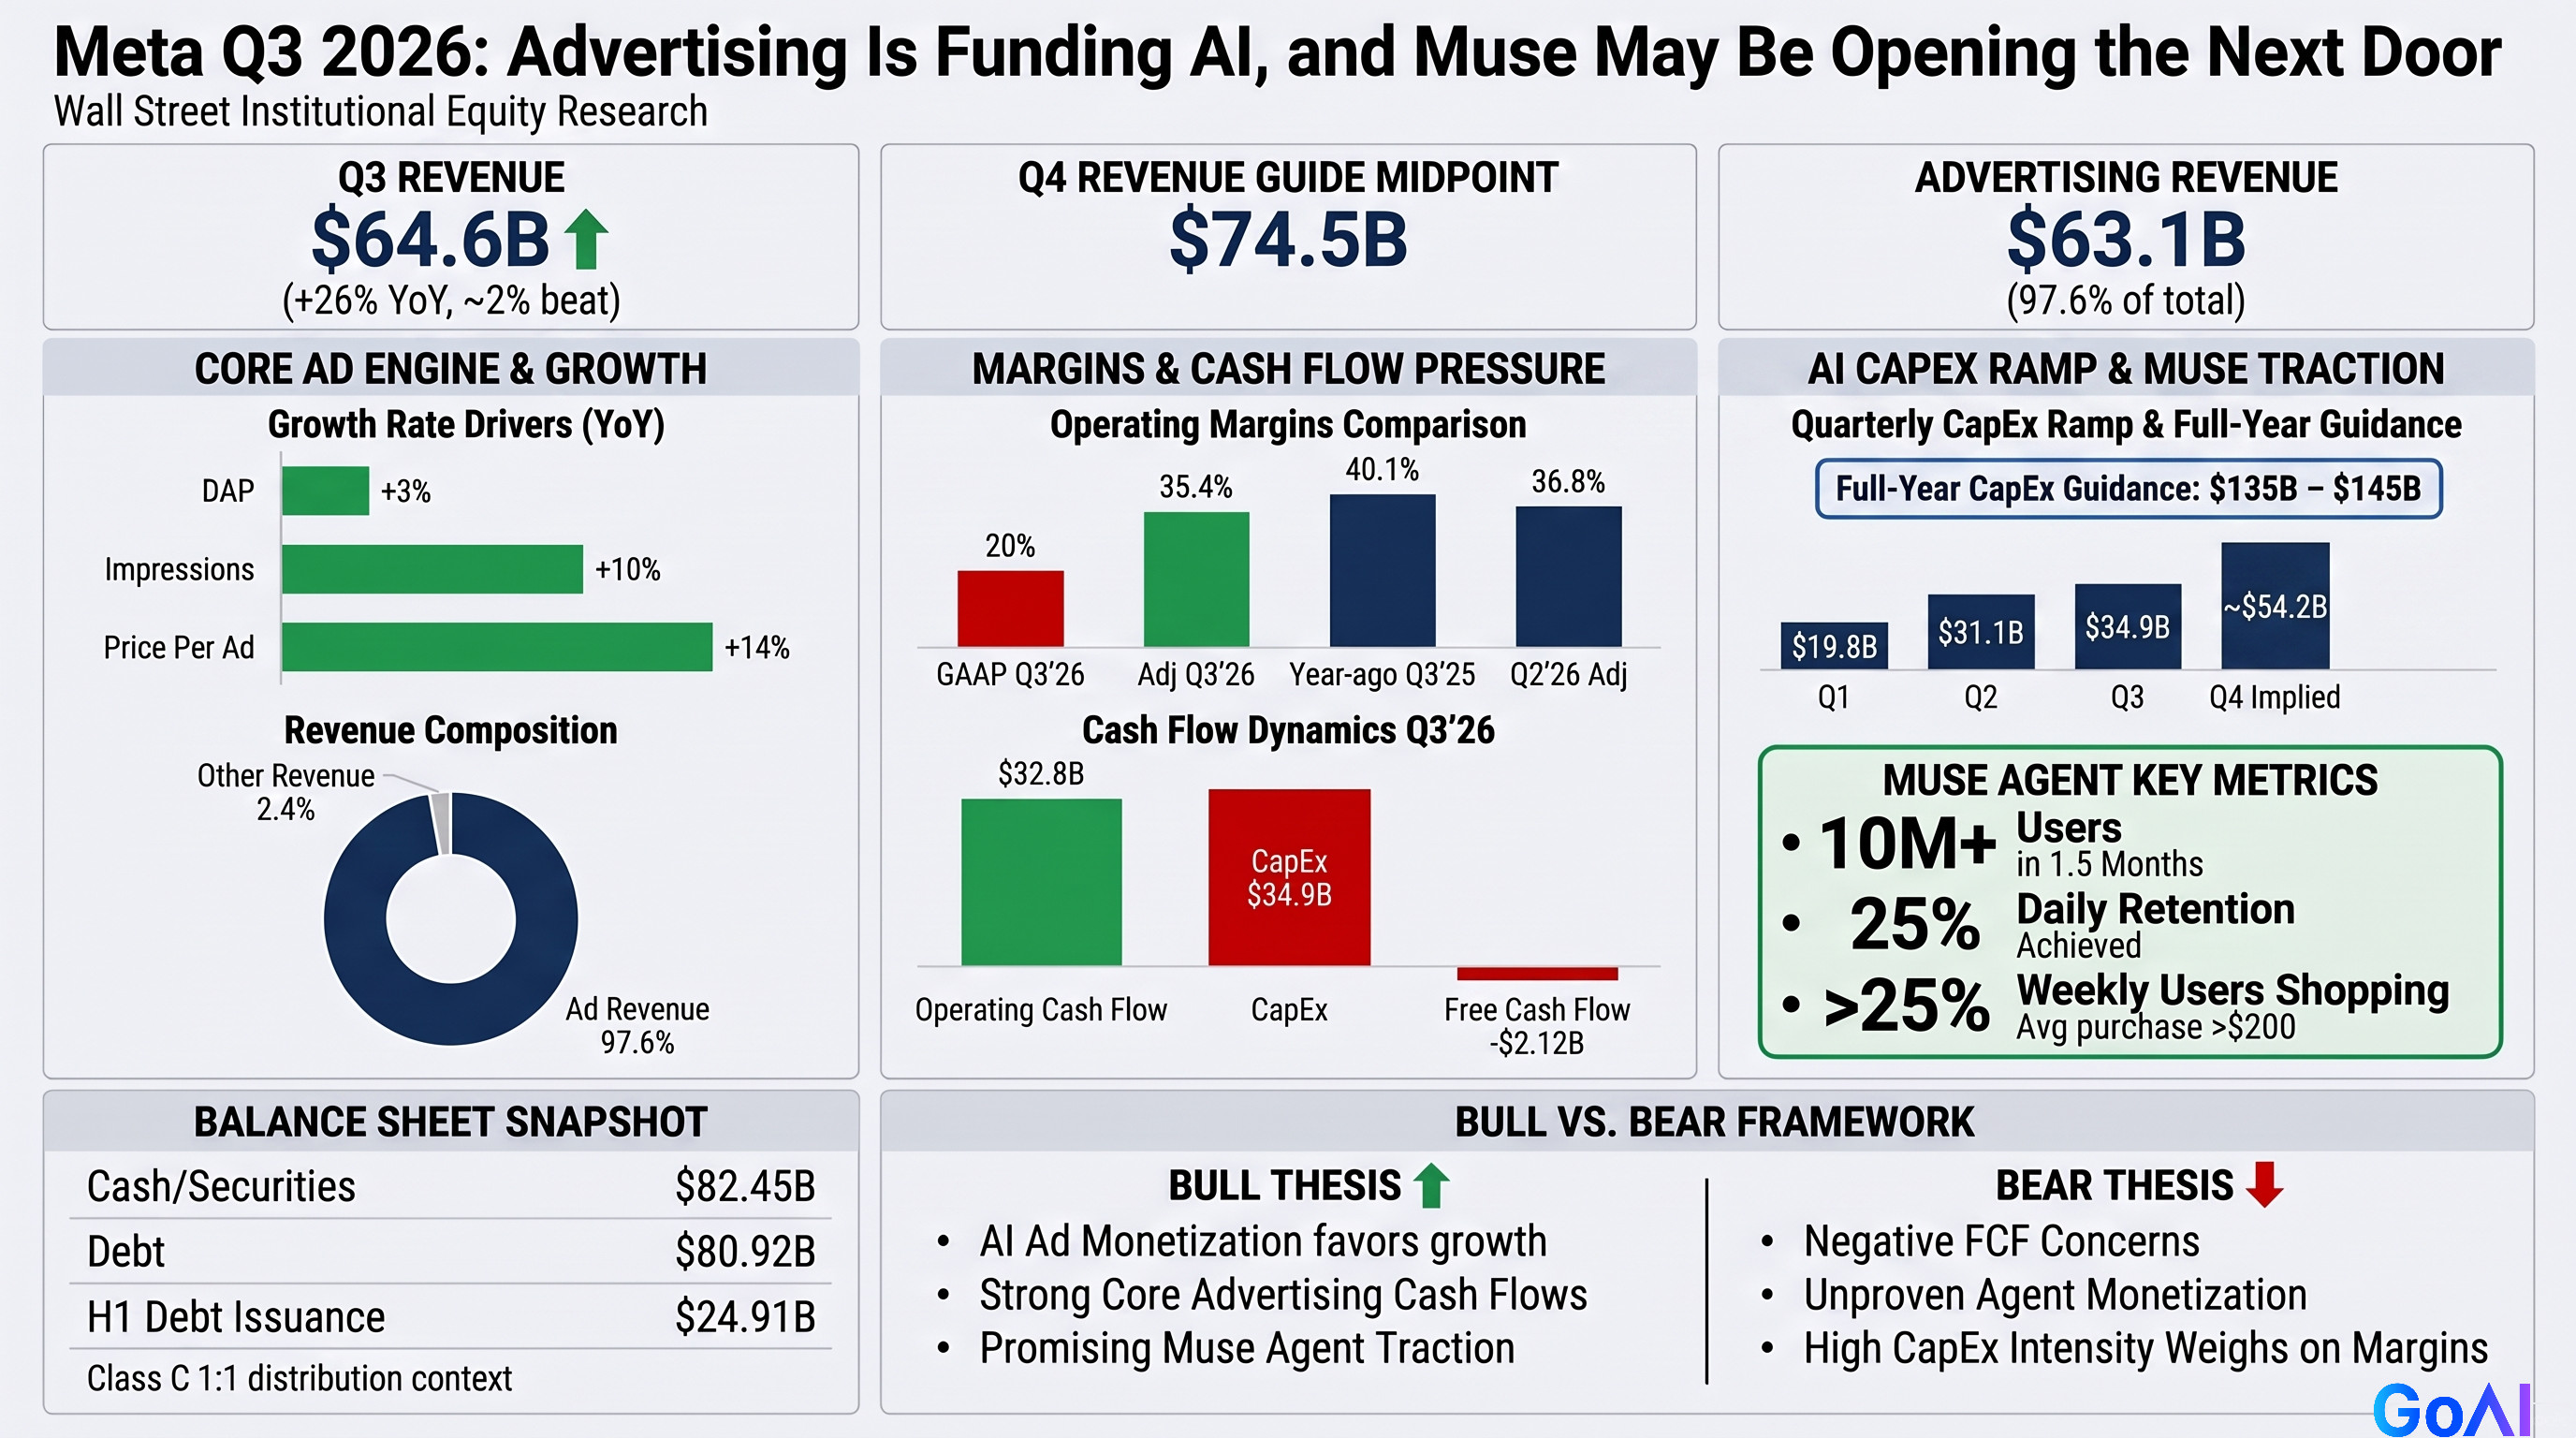
Meta generated $64.6 billion of revenue in the third quarter, up 26% year over year and roughly 2% above consensus.
Its fourth-quarter revenue outlook has a midpoint of $74.5 billion, modestly above expectations as well.
On their own, those figures are not sensational. But they matter in the context of a company simultaneously building data centers, hiring elite AI talent, and accelerating its model and product roadmap—without allowing the core advertising engine to lose momentum.
One set of data tells the story particularly…