
Fed Decision Day: Where Is the Trade Beyond the Expected Hold?
The market has already made its call on the decision.
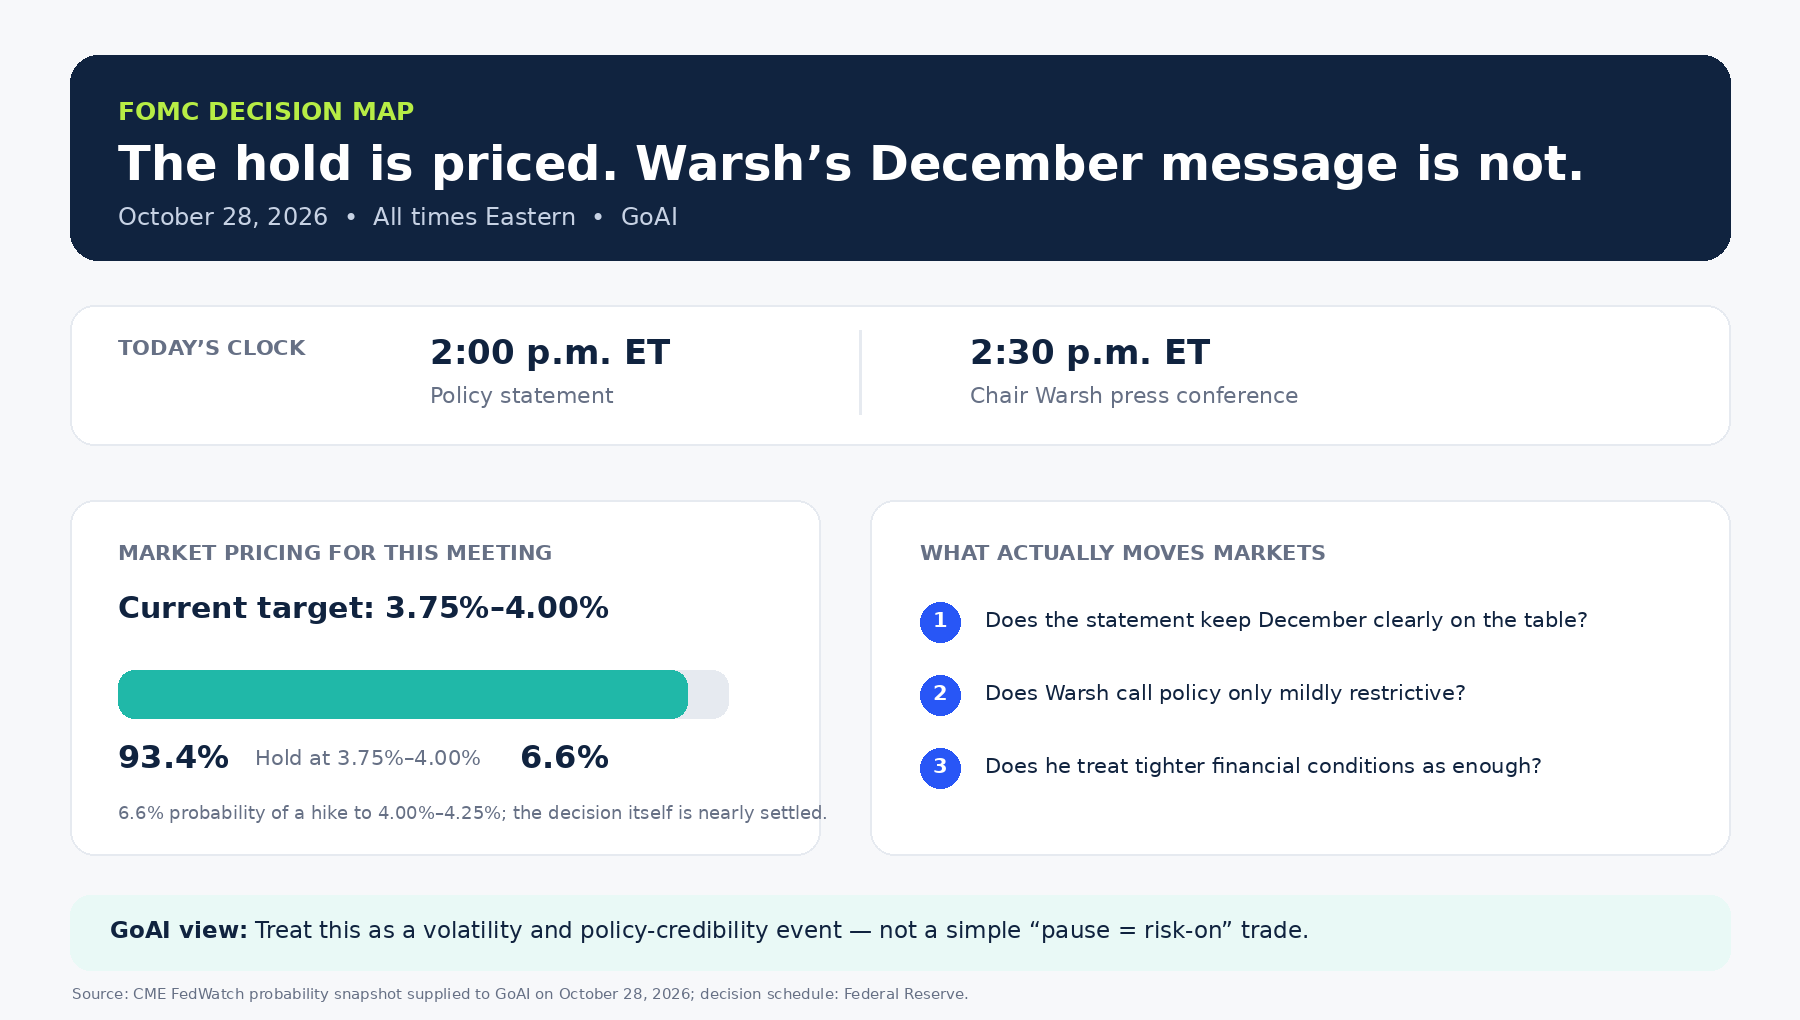
The Federal Reserve leaves the target range at 3.75%–4.00%, versus a 6.6% probability of a 25-basis-point hike.
That means the rate decision is not the trade. Warsh’s explanation for pausing is the trade.
A hold is easy to understand mechanically.
The harder question is why the Fed raised rates in September, then decided six weeks later to wait — while inflation remains above target, activity has held up, and the Committee’s own September minutes said that most participants thought another increase would likely be appropriate before year-end.
At GoAI, we do not view a hold as a clean risk-on signal. This is a policy-credibility and rate-volatility event. The pause is largely priced; what is not fully priced is whether Warsh leaves December clearly open, and whether investors believe the Fed still has a coherent reaction function.
The data do not give Warsh an easy way to sound relaxed
The September employment report was soft at first glance: nonfarm payrolls rose just 29,000 and July–August payrolls were revised down by a combined 60,000. But unemployment held at 4.2%, and average hourly earnings were up 3.0% from a year earlier.
Inflation tells the other side of the story. Headline CPI rose 0.6% in September and 3.7% over 12 months.
Core CPI gained 0.3% on the month and 2.6% year on year. Gasoline explained more than half of the monthly headline increase, but shelter, airline fares, recreation, used cars, education, medical care, and apparel also rose during the month.
That is not an economy demanding…